
Clean energy, firmly contracted
Long-term data-centre demand can anchor new geothermal capacity, with renewable certificates from PLN. Warta Ekonomi, Dec 2025CNBC Indonesia, 12 Sep 2024
Investor dossier · data centres & AI compute
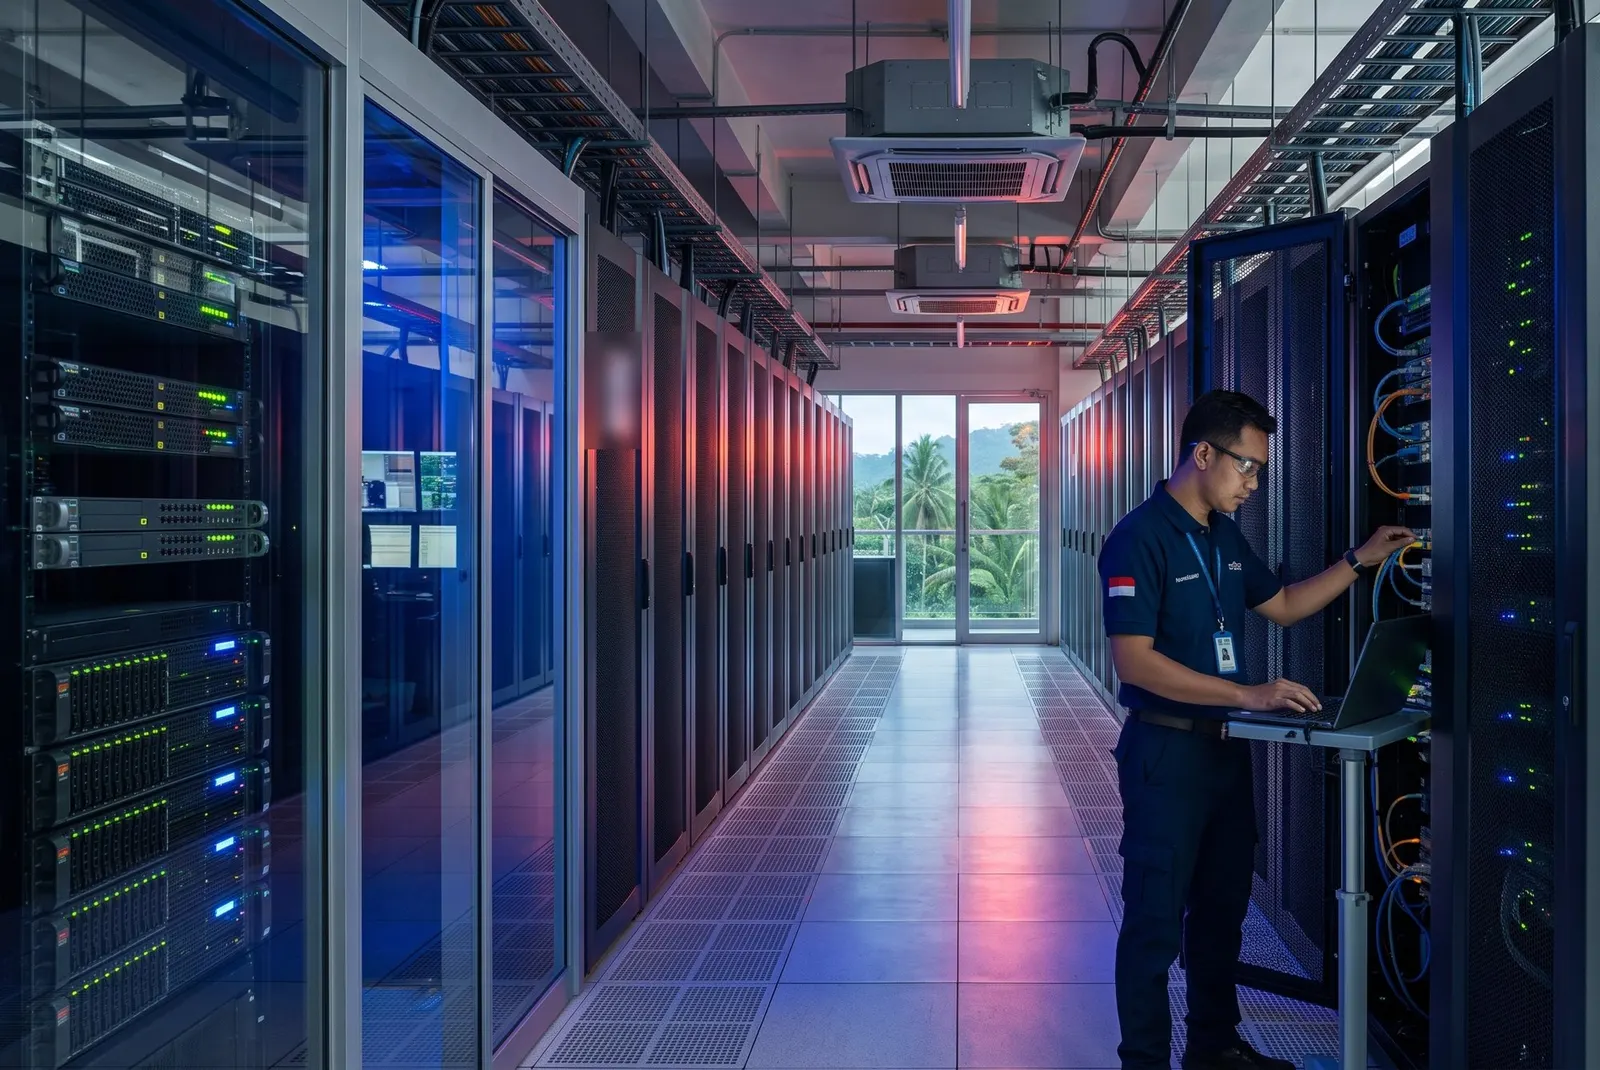
Two trans-Pacific cables land at Manado, geothermal power runs at Lahendong, and Indonesia keeps regulated data at home. This dossier answers the questions a cloud provider, colocation developer or infrastructure fund asks first, with a source for every figure and the weak points stated openly.
Sources: IndoTelko, Apr 2017CNBC Indonesia, 13 Feb 2025PGE, LahendongPLN via Sulut Review, 16 Aug 2026CNBC Indonesia, 4 Nov 2026
Estimated investment to build the AI hub: US$ 1.2 B to 100 MW in phases (construction; US$ 1.7 B – US$ 1.8 B with new generation if needed; tenant IT and GPUs excluded) · Phase 1: from US$ 100 M (about 8.4 MW) (estimate) See the phases
Scorecard
The five questions a hyperscaler site team asks first, side by side. Every cell has a source and a date; where we found no reliable source, the cell says so.
| Criterion | North Sulawesi | Johor | Batam | Singapore |
|---|---|---|---|---|
| Power price | PLN tariff I-4 (high voltage): Rp 996.74 per kWh, Q4 2026 CNBC Indonesia, 4 Nov 2026 | About 60 sen per kWh, new TNB ultra-high-voltage class (analyst estimate) Light Reading (TNB 2025 tariff) | PLN Batam I-4 (above 30 MVA): Rp 968 per kWh off-peak, Rp 1,066 at peak, Q1 2026 PLN Batam tariff, Jan–Mar 2026 | S$ 0.2859 per kWh, regulated low-voltage tariff, Q4 2026; data-centre contract prices are not public SP Group tariff Q4 2026 (via GetSolar) |
| Green share of the grid | About 27% renewable in the North Sulawesi–Gorontalo grid, mostly geothermal (PLN, November 2026) PLN UID Suluttenggo via SulutDaily, 6 Nov 2026 | Malaysia: 21% low-carbon electricity in 2025 (national; no Johor figure published) Ember: Malaysia, 2025 | Not published in our sources | Natural gas made 93.1% of electricity in 2025; solar and all other sources about 7% EMA: fuel mix for electricity generation |
| Land | Taxable land value (NJOP) in KEK Bitung about Rp 800,000–1,000,000 per m² (April 2026); the zone covers about 534 ha Sulut Review, 3 May 2026Antara, 11 Jun 2026 | Not published in our sources | Not published in our sources | Scarce: new capacity only through government calls; the second call gave 200 MW to four operators (August 2026) W.Media, Aug 2026 (DC-CFA2) |
| Latency to Singapore | Not measured: no public probe in North Sulawesi. Nearest public probes: 71.4 ms from General Santos, Philippines (520 km away); 20.8 ms from Banjarmasin, Indonesia (1,257 km away) RIPE Atlas measurement 30715243RIPE Atlas probe 7611RIPE Atlas probe 7108 | Not measured: no RIPE Atlas anchor in Johor | 1.9 ms from a Batam anchor (Jan 31, 2026 to Feb 7, 2026, its last week online) RIPE Atlas measurement 30715243RIPE Atlas probe 7276 | 0.4 ms inside Singapore (reference) RIPE Atlas measurement 30715243RIPE Atlas probe 7092 |
| Moratorium and permits | No moratorium. KEK Bitung does not yet list data centres; the draft data-centre regulation names Bitung (October 2026) CNBC Indonesia, 23 Oct 2026Kompas, 24 Jun 2026 | Tighter since November 2025: no new Tier 1 and Tier 2 centres, reclaimed water required New Straits Times, Nov 2025 | No moratorium found; BP Batam reports more than Rp 120 trillion in nine data-centre projects (2026) BP Batam / Diskan Batam, 2026 | Selective: winners of the second call must run more than half their capacity on green energy (August 2026) W.Media, Aug 2026 (DC-CFA2) |
Values are as published and not like-for-like: regulated tariffs, an analyst estimate and national grid shares. Rupiah and other currencies are not converted here; see the cost comparison below.
Round-trip time (ping) measured by RIPE Atlas, the open internet measurement network. There is no public probe in North Sulawesi, so we show the nearest public probes and say where they are. These are not measurements from Manado.
Median of every ping reply over seven days (4 measurements, 5,942 to 7,527 replies per line). Snapshot taken on Nov 14, 2026; probes that went offline show their last week online. Hawaii: no public anchor. A carrier measurement from Manado is still to be done. Sources: RIPE Atlas measurement 30715243RIPE Atlas measurement 39433115RIPE Atlas measurement 28697410RIPE Atlas measurement 25787507
The grid that serves North Sulawesi, Gorontalo and Central Sulawesi on 16 August 2026, with Lahendong geothermal on the same scale.
Rp 996.74 PLN tariff I-4, Q4 2026
Lahendong is part of the available capacity, not on top of it. A campus of tens of megawatts needs new capacity agreed with PLN. PLN via Sulut Review, 16 Aug 2026PGE, LahendongCNBC Indonesia, 4 Nov 2026
SEA-US lands at Kauditan, North Minahasa; Bifrost lands at Manado. Lines join the North Sulawesi landing to the other landing points of the same cable. They are schematic, not the route on the seabed.
North Sulawesi invites a long-term partner to build an AI campus on Indonesia’s Pacific coast: where two trans-Pacific cables come ashore, where geothermal power runs around the clock, and where the province tailors site, power and permits to your roadmap.
SEA-US and Bifrost connect the province directly to Guam, Hawaii and the US west coast, and to Singapore and Jakarta. Submarine Cable Map: SEA-USCNBC Indonesia, 13 Feb 2025
Lahendong supplies 120 MW today, with 410 MWe of resource at Kotamobagu and 350 MWe at Lahendong: a path to round-the-clock carbon-free goals such as Google’s for 2030. PGE, LahendongKompas, 7 Feb 2024Google: 24/7 carbon-free by 2030
About 2,173 km from Jakarta and 2,314 km from Batam: geographic diversity for in-country availability zones and disaster recovery.
Public-scope systems must keep data in Indonesia and the data-protection law applies in full; data hosting is open to 100% foreign ownership. PP 71/2019 (BPK JDIH)UU 27/2022 (BPK JDIH)Perpres 10/2021 (BPK JDIH)
The same PLN industrial tariff as Jakarta (Rp 996.74 per kWh, Q4 2026) and land for a campus that grows to about 100 MW. CNBC Indonesia, 4 Nov 2026
Bitung was put forward as a data-centre location in June 2026 and is named in the draft data-centre regulation; one provincial counterpart for site, permits and power. Kompas, 24 Jun 2026CNBC Indonesia, 23 Oct 2026
A hyperscaler will find these in its first week. We list them first.
The questions site-selection teams ask, in their order. Every answer gives its source; where we found no source, we say so and do not estimate.
The months are our planning estimate, not a commitment by PLN or any authority.
30 minutes with the team on your requirements: megawatts, timeline, certifications.
We coordinate a bankable site study with DPMPTSP North Sulawesi, PLN and the KEK Bitung administrator: power, ground, hazards, land, fibre, design and cost (see below).
Sources, maps, tariff decisions, free-zone documents and this dossier as PDF.
A visit to the cable-landing area, KEK Bitung, Lahendong and PLN.
What infrastructure funds and developers (Blackstone and AirTrunk, KKR and STT GDC, GIP and BlackRock’s AI partnership, Stonepeak and Digital Edge, EdgeConneX, DayOne, Princeton Digital, NTT, BDx, DCI, NeutraDC) have shown they need in their deals, and what North Sulawesi can show today. Most groups publish no fixed thresholds, so the “what they need” column is drawn from their published deals.
| Requirement | What investors need (from their deals) | Status in North Sulawesi | What we must deliver |
|---|---|---|---|
| Scale | Platform campuses start at about 100 MW: the Equinix xScale joint venture with GIC and CPP builds campuses above 100 MW; AirTrunk’s first Johor campus is 150 MW; Digital Edge plans 500 MW near Jakarta. Smaller first builds exist: NeutraDC Batam with Singtel is 18 MW. | Missing Grid reserve of about 174 MW for the whole region: a first phase of a few MW up to about 20 MW is realistic, 100 MW is not without new plants. | A phased plan: phase 1 sized to what PLN can connect, later phases tied to new geothermal units. DCD: Equinix xScale JV, Oct 2024Baxtel: AirTrunk Johor, Jul 2026Investortrust: PLN–Digital Edge 2 × 725 MVAThe Tech Capital: NeutraDCPLN via Sulut Review, 16 Aug 2026 |
| Power certainty | A signed PLN supply agreement before construction: Digital Edge signed with PLN in October 2025 for its Cikarang campus, now 2 × 725 MVA. | Missing No data-centre supply agreement or connection study in North Sulawesi yet. | A PLN UID Suluttenggo connection study and a memorandum of understanding for a named site. Investortrust: PLN–Digital Edge 2 × 725 MVABisnis.com, 4 Jul 2025 |
| Green power | Google aims for 24/7 carbon-free energy by 2030; Microsoft has a 100/100/0 goal for 2030. Lenders give green loans (AirTrunk Johor, Princeton Digital Jakarta). | In progress Lahendong geothermal (120 MW) and PLN certificates exist; Lahendong units 7–8 are being evaluated. | A written PLN offer for certificates or dedicated geothermal-backed supply. Google: 24/7 carbon-free by 2030GeekWire 2026: Microsoft 100/100/0Baxtel: AirTrunk Johor, Jul 2026DCD: PDG green loanWarta Ekonomi, Dec 2025CNBC Indonesia, 12 Sep 2024 |
| Anchor tenant | Build-to-suit and pre-leases of 10–15 years with a creditworthy tenant before building (industry primers; AirTrunk’s first Johor campus was fully contracted). | Missing No anchor tenant yet. | An anchor strategy: Telin and carriers, banks’ disaster-recovery sites, public-scope cloud, AI-inference customers in eastern Indonesia and the Philippines. CREFC data-centre primer, 25 Feb 2026Baxtel: AirTrunk Johor, Jul 2026 |
| Land and title | Industrial-estate land with clear building rights (HGB). | In progress KEK Bitung (about 534 ha) has a manager, but data centres are not yet one of its activities; other plots are unverified. | A land bank of clean-title plots with data-centre zoning, and a KEK decision to admit data centres. Antara, 11 Jun 2026Kompas, 2023 (KEK Bitung land)Kompas, 24 Jun 2026 |
| Connectivity | Diverse fibre to the main exchanges and cable landings. | In progress Two trans-Pacific cables and neuCentrIX are in place; no internet-exchange node and unverified domestic diversity. | Carrier offers for two separate routes, and a local exchange node with the carriers. IndoTelko, Apr 2017DCD: Telin Bifrost CLS ManadoTelkom, Jan 2019 |
| Hazard data | Site-specific seismic, tsunami and flood data. | Missing Regional data only (BMKG, USGS, InaRISK). | A feasibility study with a geotechnical and seismic survey per shortlisted plot. USGS earthquake catalogueBNPB InaRISK |
| Rules and incentives | Clear ownership and data rules; predictable incentives. | In progress 100% foreign ownership and data localisation are clear; a draft data-centre regulation names Bitung; the tax holiday is not being extended for now. | Follow the draft regulation and the free-zone route; give investors a dated status. Perpres 10/2021 (BPK JDIH)PP 71/2019 (BPK JDIH)CNBC Indonesia, 23 Oct 2026CNBC Indonesia, 5 Nov 2026 |
| Country risk and protection | Investment-grade sovereign rating and treaty protection. | Available S&P BBB stable (July 2026); Moody’s Baa2 and Fitch BBB, both with a negative outlook (February and March 2026). The Indonesia–Singapore investment treaty (in force since March 2021) allows international arbitration. | Explain holding structures with legal advisers; this is national, not provincial. The Diplomat, Jul 2026 (S&P)Bank Indonesia, Feb 2026 (Moody’s)KTWB, 4 Mar 2026 (Fitch)UNCTAD: Indonesia–Singapore BIT 2018 |
| Currency | Long contracts, often priced in US dollars abroad. | Missing Domestic transactions must be in rupiah (Currency Law 7/2011, Bank Indonesia rule 17/3/PBI/2015); exemptions are narrow. | Legal advice on tariff indexation and offshore contracts. Clifford Chance, May 2015 |
| Returns and exit | Stabilised data-centre cap rates of about 5.0–7.5% (US, first half 2026); exits through REITs and stake sales (NTT DC REIT in Singapore, July 2025; KKR and Singtel’s purchase of STT GDC, 2026). | Missing No operating data centre to value in North Sulawesi. | A first project with a bankable tenant, so a track record exists. Houlihan Lokey, Oct 2026Mingtiandi: NTT DC REIT, Jul 2025STT GDC, Sep 2026 |
| Sovereign co-investor | Local partners reduce risk: Indonesia’s sovereign fund INA invested in DayOne’s Batam campus; Danantara plans a data-centre platform. | Missing No sovereign co-investor in a North Sulawesi project. | An approach to INA and Danantara with a concrete site and power plan. Mingtiandi: INA in DayOneAntara, 2026 (Danantara) |
Status as of 13 November 2026. Available = exists and is sourced; In progress = announced, drafted or under evaluation; Missing = not found.
Six areas, scored on six criteria from the sourced facts in this dossier. The scores are our own assessment, not a study: a feasibility study per plot comes first.
Positions are approximate area centres, not plots. Orange-ringed points marked “possible, to be studied” are ideas for new infrastructure: none is planned, financed or approved.
| Area | Power 25% | Connectivity 20% | Land 15% | Hazards 20% | Rules & incentives 10% | Access & talent 10% | Score (of 100) |
|---|---|---|---|---|---|---|---|
| Kauditan and Kema cable corridor (North Minahasa)AI or cloud campus (10 MW and more) | 3 | 5 | 4 | 3 | 3 | 4 | 73 |
| Mapanget, Manado (airport area)Colocation (1–10 MW) | 3 | 4 | 3 | 3 | 3 | 5 | 68 |
| KEK Bitung (Tanjung Merah)AI or cloud campus (10 MW and more) | 3 | 3 | 4 | 2 | 4 | 4 | 63 |
| Lahendong and Tomohon (geothermal area)Edge or pilot (under 1 MW) | 4 | 2 | 2 | 2 | 3 | 3 | 54 |
| Kotamobagu (Bolaang Mongondow)Long term | 3 | 1 | 3 | 3 | 3 | 2 | 50 |
| KEK LikupangNot recommended | 2 | 3 | 2 | 2 | 1 | 3 | 44 |
Next to the SEA-US landing station, between Manado and Bitung: the best connectivity in the province and room for a campus. The east coast receives tsunami warnings, so choose a site set back and on higher ground.
2 km from the SEA-US landing · 27 km from Lahendong · 17 km from the port of Bitung (straight line)
Close to Telkom’s neuCentrIX, the airport, customers and staff: right for colocation, interconnection and a first phase of a few megawatts. Plots are smaller; avoid low land that floods.
26 km from the SEA-US landing · 30 km from Lahendong · 32 km from the port of Bitung (straight line)
A 534 ha free zone with a manager, close to the port, and named by the government as a candidate data-centre location. It needs the zone to admit data centres, a fibre link to the landing stations and coastal hazard design.
7 km from the SEA-US landing · 35 km from Lahendong · 9 km from the port of Bitung (straight line)
Next to the 120 MW geothermal field: the strongest green-power story. A volcanic area with hilly land and no cable landing: suited to edge and pilot sites, or as a power source for a campus elsewhere through PLN.
30 km from the SEA-US landing · 1 km from Lahendong · 45 km from the port of Bitung (straight line)
A large geothermal resource (about 410 MWe) and planned PLN geothermal units (2031 and 2033). Far from the cables and from Manado: a long-term option if new geothermal capacity is built.
111 km from the SEA-US landing · 84 km from Lahendong · 126 km from the port of Bitung (straight line)
A tourism free zone (197 ha). Data centres are not among its activities, and the coast serves resorts: not recommended.
34 km from the SEA-US landing · 51 km from Lahendong · 29 km from the port of Bitung (straight line)
A dedicated high-voltage substation between Kauditan and Bitung with two independent feeds, to be studied with PLN.
A PLN supply contract tied to Lahendong units 7–8 or a new geothermal unit, with certificates.
Two physically separate routes between the landing stations, a campus and neuCentrIX.
A branch or new domestic cable landing at Bitung, which the government called an untapped landing point in June 2026.
A node of a national exchange with the carriers, so traffic in eastern Indonesia stays local.
Seawater heat rejection for a coastal campus, subject to environmental approval.
Published figures only, each with its source. Where North Sulawesi has no published figure, the cell says “to be quoted”.
| Hub | Power price (as published) | ≈ per kWh, in your currency | Build cost per MW (T&T 2026–27) | Colocation rent per kW per month (CBRE) | Sources |
|---|---|---|---|---|---|
| North Sulawesi | PLN I-4 (≥ 30 MVA): Rp 996.74/kWh | US$ 0.055 | to be quoted | to be quoted | CNBC Indonesia, 4 Nov 2026 |
| Jakarta | PLN I-4 (≥ 30 MVA): Rp 996.74/kWh | US$ 0.055 | US$ 12 M | not published in our sources | CNBC Indonesia, 4 Nov 2026EdgeProp, Oct 2026 (T&T 2026–27) |
| Batam | PLN Batam I-4 (> 30 MVA): Rp 968/kWh off-peak, Rp 1,066/kWh peak (Q1 2026); converted at the off-peak rate | US$ 0.053 | not in the index | not published in our sources | PLN Batam tariff, Jan–Mar 2026 |
| Johor | about 60 sen/kWh, new TNB ultra-high-voltage class (analyst estimate) (estimate) | – | US$ 10.1 M | not published in our sources | Light Reading (TNB 2025 tariff)EdgeProp, Oct 2026 (T&T 2026–27) |
| Singapore | S$ 0.2859/kWh regulated low-tension tariff, Q4 2026 (data-centre contract prices not public) | – | US$ 15.4 M | US$ 330 – US$ 475 | SP Group tariff Q4 2026 (via GetSolar)Turner & Townsend APAC, 29 Oct 2026CBRE Global DC Trends 2026, 17 Jun 2026 |
| Northern Virginia | Virginia industrial average 9.98 US cents/kWh, Aug 2026 | US$ 0.100 | US$ 11.8 M | US$ 190 – US$ 235 | US EIA Electric Power Monthly, 23 Oct 2026Turner & Townsend DCCI 2026–27, 22 Oct 2026CBRE Global DC Trends 2026, 17 Jun 2026 |
| Dublin | € 0.2552/kWh, Ireland non-household 500–2,000 MWh band, H2 2025 | – | US$ 12.6 M | not published in our sources | Eurostat, 8 May 2026Turner & Townsend DCCI 2026–27, 22 Oct 2026 |
| Nordics (build cost: Stockholm) | Sweden € 0.0970, Finland € 0.0748/kWh, same Eurostat band, H2 2025 | – | US$ 13.9 M | not published in our sources | Eurostat, 8 May 2026Turner & Townsend DCCI 2026–27, 22 Oct 2026 |
| Tokyo | about ¥ 28.26/kWh business average, Mar 2026 (negotiated data-centre prices not public) | – | US$ 18.3 M | US$ 280 | GlobalPetrolPrices, Mar 2026Turner & Townsend APAC, 29 Oct 2026CBRE Global DC Trends 2026, 17 Jun 2026 |
| Osaka | about ¥ 28.26/kWh business average (national), Mar 2026 | – | US$ 17.2 M | not published in our sources | GlobalPetrolPrices, Mar 2026Turner & Townsend APAC, 29 Oct 2026 |
| Manila | not published in our sources | – | US$ 9.6 M | not published in our sources | EdgeProp, Oct 2026 (T&T 2026–27) |
| Ho Chi Minh City | VND 1,811/kWh normal hours, industry ≥ 110 kV (EVN, May 2025) | – | US$ 8.3 M | not published in our sources | EVN: Decision 1279/QD-BCT, May 2025Turner & Townsend APAC, 29 Oct 2026 |
The question every investor asks first. The hub is built in phases to about 100 MW of IT load. These are indicative construction costs from a published index, not a quote for North Sulawesi; what the index leaves out is listed separately.
Phase 1: from US$ 100 M (about 8.4 MW) Phase 1 math: US$ 100 M ÷ US$ 11.96 per watt (Jakarta, Turner & Townsend 2026–27) = about 8.4 MW of IT load, construction only; a first hall of 10 MW is about US$ 119.6 M. (estimate)
| Phase | IT load, cumulative | Grid supply to ask PLN for (IT load × PUE 1.3–1.54) | Construction in this phase | Construction, cumulative (Jakarta basis) | Cumulative, regional span (Johor to Singapore) |
|---|---|---|---|---|---|
| Phase 1 | 10 MW | 13–15.4 MW | US$ 119.6 M (estimate) | US$ 119.6 M | US$ 100.6 M – US$ 153.9 M |
| Phase 2 | 25 MW | 32.5–38.5 MW | US$ 179.4 M (estimate) | US$ 299 M | US$ 251.5 M – US$ 384.8 M |
| Phase 3 | 50 MW | 65–77 MW | US$ 299 M (estimate) | US$ 598 M | US$ 503 M – US$ 769.5 M |
| Phase 4 | 100 MW | 130–154 MW | US$ 598 M (estimate) | US$ 1.2 B | US$ 1 B – US$ 1.5 B |
EdgeProp, Oct 2026 (T&T 2026–27)Turner & Townsend APAC, 29 Oct 2026AKCP, 23 Jul 2026 (Singapore roadmap)Uptime Institute survey 2025
Reference points from announcements, each with its source. Amounts are what was announced: a total investment, a loan, or a multi-year programme without a capacity. US$ per MW is our own division, shown only for a total investment with a capacity.
| Project | Capacity | Amount | What the amount is | Per MW (our division) | Source |
|---|---|---|---|---|---|
| Digital Edge CGK campus, Bekasi–Cikarang (Stonepeak) | 500 MW | US$ 4.5 B | total investment: design capacity; PLN supply 2 × 725 MVA | US$ 9 M (estimate) | Investortrust: PLN–Digital Edge 2 × 725 MVA |
| AirTrunk JHB2, Johor (Blackstone) | 270 MW | US$ 2.3 B | loan or financing: 270 MW and more; green loan, July 2026 | – | Baxtel: AirTrunk Johor, Jul 2026 |
| EdgeConneX, Bekasi (EQT) | 120 MW | US$ 403.8 M | loan or financing: up to 120 MW; sustainability-linked financing, December 2024 | – | DCD: EdgeConneX Indonesia |
| Princeton Digital JC2, Jakarta | 22 MW | US$ 105 M | loan or financing: 22 MW; loan converted to green financing | – | DCD: PDG green loan |
| Equinix JK1, Jakarta | – | US$ 74 M | total investment: opened May 2025; capacity not stated | – | Equinix, 15 May 2025 |
| Microsoft, Indonesia | – | US$ 1.7 B | multi-year programme: cloud and AI, 2024–2028 | – | Microsoft, 30 Apr 2024 |
| Amazon Web Services, Jakarta region | – | US$ 5 B | multi-year programme: planned over 15 years from 2021 | – | TechNode Global, 14 Dec 2021 |
A loan or financing covers part of a project, so it is not a cost per MW. Capacities are as announced (design or contracted), not built.
Three ways to spend the first US$ 100 million, worked out from the same published figures. The splits are estimates with the method shown; land, grid connection and fibre are to be quoted and reduce what is left for buildings.
For a developer or fund that leases space and power; the tenant brings its own IT and GPUs.
US$ 100 million at the Jakarta index builds about 8.4 MW of IT load, construction only, in a Tier III design. Turner & Townsend’s split of construction cost for an air-cooled data centre (US projects, 2025 index) shows where it goes: (estimate)
| Electrical: switchgear, UPS, generators, distribution | 54% of construction | US$ 54 M |
|---|---|---|
| Mechanical and cooling | 22% of construction | US$ 22 M |
| Shell and architectural | 14% of construction | US$ 14 M |
| Contractor costs | 10% of construction | US$ 10 M |
On top, to be quoted: land and site preparation, the PLN connection with a two-feed substation, diverse fibre to the SEA-US landing at Kauditan and to Bifrost, security and building management outside the contractor’s scope, design fees and contingency. Each reduces the megawatts US$ 100 million buys.
EdgeProp, Oct 2026 (T&T 2026–27)Turner & Townsend DCCI 2025: cost trendsFor an AI or cloud company that owns its hardware and wants capacity in Indonesia.
One NVIDIA GB200 NVL72 rack draws about 120 kW (NVIDIA) and was estimated at about US$ 3 M (HSBC, 2024; NVIDIA publishes no price). That is about US$ 25 M of hardware per MW of IT load, about twice the building. Building (US$ 12 M per MW) plus racks (US$ 25 M per MW) is about US$ 37 M per MW, so US$ 100 million buys about 2.7 MW, or about 22 racks, before land, grid, fibre, networking and storage. On the all-in figure of Nvidia’s CEO (US$ 50–60 million per MW) it would be 1.7–2 MW. (estimate)
NVIDIA DGX GB rack user guide, Sep 2026Tom’s Hardware, May 2024 (HSBC estimate)CNBC, 22 Sep 2025 (Nvidia CEO on cost per gigawatt)EdgeProp, Oct 2026 (T&T 2026–27)For a long-term investor who wants room to grow with demand and new geothermal power.
Phase 1 builds a 5 MW hall (US$ 59.8 M construction at the Jakarta index) and leaves about US$ 40.2 M of the US$ 100 million for land for the whole campus, a substation and grid connection sized for later phases, diverse fibre and the studies. Whether that is enough depends on PLN’s connection offer and the land price: the feasibility study answers it. Later halls follow demand. (estimate)
EdgeProp, Oct 2026 (T&T 2026–27)Our assessment: option C fits North Sulawesi best today, because the grid reserve is limited and there is no anchor tenant yet; option A fits once a tenant signs; option B fits a tenant with its own GPU programme. All amounts are estimates; each card shows its method.
The order of magnitude behind a full campus, item by item. Construction and new generation are estimates from published indices; what has no published price is marked “to be quoted”. GPUs and IT equipment are the tenant’s and are not included.
| Item | Amount | Basis |
|---|---|---|
| Construction, 100 MW of IT load | US$ 1.2 B (estimate) | 100 MW × US$ 11.96 per watt, Turner & Townsend 2026–27, Jakarta basis, construction only. EdgeProp, Oct 2026 (T&T 2026–27) |
| New generation, if PLN cannot supply from the grid | US$ 522 M – US$ 618.3 M (estimate) | The campus draws 130–154 MW from the grid (PUE 1.3–1.54); the reserve of all of Suluttenggo is about 174 MW. Priced at IRENA’s 2024 global average for new geothermal plants (US$ 4,015 per kW; eight plants, range US$ 1,217 to US$ 6,724 per kW). Whether it is needed, and whether PLN, PGE or an independent producer builds it, is to be studied. IRENA, Renewable Power Generation Costs in 2024PLN via Sulut Review, 16 Aug 2026AKCP, 23 Jul 2026 (Singapore roadmap)Uptime Institute survey 2025 |
| Grid connection, substation, fibre and land | to be quoted | No published price for Suluttenggo; PLN, the carriers and the land owner quote them in the feasibility study. |
| GPUs and IT equipment | tenant-funded, not included | For reference only: Nvidia’s CEO put an AI data centre at about US$ 35 M of Nvidia hardware per MW (2025). CNBC, 22 Sep 2025 (Nvidia CEO on cost per gigawatt) |
Order of magnitude before the items to be quoted: about US$ 1.7 B – US$ 1.8 B (construction plus new generation); construction alone US$ 1.2 B. Estimates, rounded.
Who funds a campus of this size: in the published deals, infrastructure funds and developers put in equity and borrow against signed tenants. Stonepeak has put more than US$ 3 billion of equity into Asia-Pacific data centres (Digital Edge, Princeton Digital); AirTrunk financed its second Johor campus with a US$ 2.3 billion green loan; EdgeConneX raised US$ 403.8 million of financing for its Bekasi campus. Industry primers describe build-to-suit and 10–15-year pre-leases with a creditworthy tenant before building. We publish no debt or equity percentages: they depend on the tenant contract and the lenders. Asia Asset: Stonepeak in Asia-PacificBaxtel: AirTrunk Johor, Jul 2026DCD: EdgeConneX IndonesiaCREFC data-centre primer, 25 Feb 2026
| Google Cloud | Jakarta cloud region since June 2020. Jakarta Post, 24 Jun 2020 |
|---|---|
| Amazon Web Services | Jakarta region since December 2021, with about US$ 5 billion planned over 15 years. TechNode Global, 14 Dec 2021 |
| Microsoft | Indonesia Central region (West Java, three availability zones) opened in May 2025, part of US$ 1.7 billion for cloud and AI from 2024. Microsoft, 27 May 2025Microsoft, 30 Apr 2024 |
| Equinix | JK1 in Jakarta opened in May 2025, about US$ 74 million. Equinix, 15 May 2025 |
| EdgeConneX | Jakarta (Bekasi) since 2023, with US$ 403.8 million of financing to expand to 120 MW. DCD: EdgeConneX Indonesia |
| Batam | The Batam authority counts more than Rp 120 trillion of data-centre investment in nine projects (2026). BP Batam / Diskan Batam, 2026 |
| Bitung | Proposed by the government as a new data-centre location (June 2026); named with Kupang in a draft regulation (October 2026). Kompas, 24 Jun 2026CNBC Indonesia, 23 Oct 2026 |
Investment ideas
A phased, AI-ready campus in the Kauditan–Bitung corridor, next to two trans-Pacific cables, with green power through geothermal-backed certificates. Sized to what PLN can connect, not to a headline.
PLN connection study, plot, seismic and hazard surveys, fibre routes, permits.
Inference, cloud and disaster-recovery capacity on a PLN I-4 supply contract with certificates. Indicative construction cost US$ 119.6 M (estimate); the hub starts from US$ 100 million (about 8 MW).
Another 15 MW, about US$ 179.4 M (estimate), once PLN confirms the connection and a second substation feed.
Another 25 MW, about US$ 299 M (estimate), only with new capacity (Lahendong 7–8, Kotamobagu geothermal or other PLN additions).
Another 50 MW, about US$ 598 M (estimate), with new generation (see Full build-out).
The costs are our estimate: megawatts × Turner & Townsend’s index for Jakarta (US$ 11.96 per watt, 2026–27), construction only, without land, grid works, new generation or GPUs. A Manado quote can be higher or lower. Phase 1 starts from US$ 100 million.
She answers from this dossier, with sources.
Shared value
The province seeks a partner whose investment advances the 2030 Agenda for Sustainable Development: clean energy, quality jobs and skills, and digital infrastructure for eastern Indonesia, delivered transparently and together with the communities of North Sulawesi.
Long-term data-centre demand can anchor new geothermal capacity, with renewable certificates from PLN. Warta Ekonomi, Dec 2025CNBC Indonesia, 12 Sep 2024
Hyperscale capacity, a neutral internet exchange and a diverse fibre ring beyond the Jakarta–Batam corridor. Telkom, Jan 2019
Permanent technical jobs in operations, power and security, with local suppliers in construction and services.
A talent programme with Sam Ratulangi University’s Faculty of Engineering in Manado. UNSRAT Faculty of Engineering, Renstra 2022–2026
Geothermal supply, a PUE target near 1.3 and closed-loop liquid cooling to limit water use. AKCP, 23 Jul 2026 (Singapore roadmap)
The province, PLN, the KEK administrator and Indonesia’s sovereign investors as possible co-investors. Antara, 2026 (Danantara)Mingtiandi: INA in DayOne
SDG icons are used for information; no UN endorsement is implied. SDGs
Lenders and tenants ask for it before land, power contracts or construction. We coordinate the feasibility study with DPMPTSP North Sulawesi, PLN UID Suluttenggo and the KEK Bitung administrator. The study decides whether a site works; we do not promise its outcome.
Connection study and supply offer from PLN: capacity, voltage, two feeds, timeline, green certificates.
Geotechnical survey and a probabilistic seismic hazard analysis (PSHA) for design to SNI 1726:2019.
Hazard check on InaRISK and a site-level assessment of inundation and drainage.
Title (HGB) check, zoning, and whether KEK Bitung admits data centres.
Route survey and carrier offers for two separate routes; measured latency to Jakarta, Singapore and Guam.
Design basis for temperature and humidity, cooling concept, water source and use.
Environmental approval route (AMDAL or UKL-UPL, depending on size).
Concept design and an early-stage (Class 4–5) cost estimate.
Demand study and anchor-tenant sounding.
Structure, lenders, green-loan eligibility and a sovereign co-investor (INA, Danantara).
Province-wide or sector-wide exclusivity is not possible: the Investment Law (UU 25/2007, art. 4(2)(a) and art. 6(1)) requires equal treatment of all investors, domestic and foreign. What is common is a reservation of a specific site for a limited time. The terms below are options to negotiate, not an offer. UU 25/2007 (JDIH Kemenkeu)
Every term needs legal review and agreement with DPMPTSP North Sulawesi and, inside a free zone, the KEK administrator and the land owner.
A free zone (KEK) gives the strongest incentives, but only for the zone’s main activities. Our assessment of the route for data centres, with its status.
Our recommendation: two tracks at once. Ask the KEK administrator and the National KEK Council to add data centres to KEK Bitung, and plan the base case on national rules without a tax holiday, so the project does not depend on either. Status 13 November 2026: neither track has started.
Your contact for the AI hub
Deputy Business Ambassador of North Sulawesi · Invest North Sulawesi
Talk to us in confidence about your requirements: megawatts, timing, power profile and latency. We arrange the site visit with DPMPTSP and PLN.
Our assessment from public sources, status 13 November 2026. Not legal, tax, engineering or investment advice. Scores and estimates are labelled as such; nothing on this page is a commitment by PLN, the government or any operator.